What You Need To Know About Credit Cards
$4371.
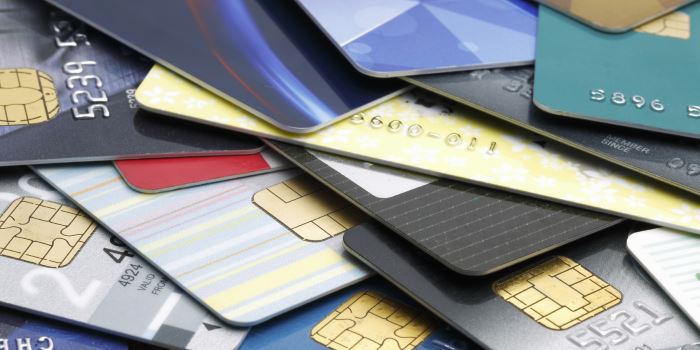
According to ASIC, that’s the average debt owed per credit card in Australia (as of this writing). That means the average Australian pays $735 in interest annually. That’s a lot of money. So, does that mean we should avoid using credit cards? Credit cards offer many benefits that make them worth considering. First, they offer convenience, meaning you don’t need to carry thick wads of cash with you all the time. As a result, it offers security, because if you lose your wallet or get robbed, you won’t lose physical cash. You just need to call the bank to cancel your card immediately. Credit cards are also a great way to keep track of your spending. The monthly statement lists your every transaction and is especially handy if you often find yourself wondering, ‘um, what happened to all my money?’ Credit cards cater to many different lifestyles. For example, dividend credit cards are usually best suited for everyday spending, while Frequent Flyer cards, as the name implies, are great for people who fly (frequently). Besides earning travel miles, such cards may come with perks including complimentary airport lounge access. Given the benefits that have been mentioned thus far, it would seem that credit cards are the perfect replacement for cash. However, don’t forget those statistics that the average credit card user pays their bank about $735 in annual interest, in addition to what they spend! I think most do so unwittingly, signing up with credit cards without having sufficient financial literacy. Be sure to do your reading before signing anything. (There are many great websites like moneysmart.gov.au that promote financial literacy.) For most, the biggest problem with credit cards is the very advantage it offers: convenience. With the possibility of spending more than what you earn, it gives you access to a lifestyle you wouldn’t have been able to afford before. While this seems tempting, it’s important to realise that everything comes at a cost. When you can’t pay your bills, you become indebted to the bank. Banks love debt because banks are businesses and a significant portion of the money they earn comes from such debt, so they are more than happy if you choose to only pay the minimum amount on your credit card every month. For example, If you only pay the minimum sum each month, a $4400 bill would take approximately 31 years to pay off (and cost $14,900 in interest), according to MoneySmart. With all that has been said, I’d still recommend credit cards, as they do often have great perks. However you really should avoid debt as much as possible. If you do have debts, endeavour to pay them off as soon as you can. I personally own about five credit cards to maximise the benefits of each, but I also have zero debt because I make it a point to pay off all my credit card bills in full. If there is one single piece of advice that I could offer, it’d be to live within your means and don’t go broke trying to look rich.Congratulations to Ian for winning this writing challenge, answering: What You Need To Know About Credit Cards. Ian wins a $50 Westfield gift card for his submission. For your chance to win, check out our latest writing challenges in our Comps section. Also, be sure to follow this guide on how to win the writing challenge!
Photo: iStock.
Comments & Feedback
Share your opinion
Emoji cheatsheet Formatting Comment guidelines