How to Use Buy Now Pay Later Apps Responsibly
We asked an expert.
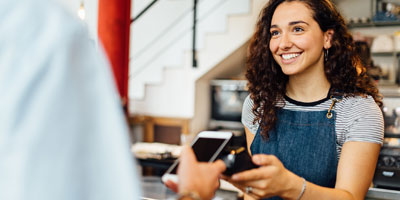
Let’s face it: we all love to treat ourselves from time to time. Whether we’re splurging on a new jacket we definitely can’t afford or buying the latest smartphone, it can be hard not to turn to Buy Now Pay Later (BNPL) apps to help us out.
BNPL apps like Afterpay and Zip Pay allow us to make purchases and pay them off over time in weekly, fortnightly or monthly repayments. Sounds pretty simple, right? Well, it can be. However, it can also be easy to fall into the trap of overusing BNPL apps.
According to the Next Gen Index, in Australia BNPL usage has surged by 174 per cent with Gen Z since January 2020, which means it’s super important for us to know how to use these apps responsibly.
As Money School’s Lacey Filipich tells Student Edge over the phone, there are definitely ways for young people to use BNPL apps sensibly.
“If you think of it as a tool, rather than the first thing you go to, you can probably find ways of using it really effectively,” she says.
“For people who find budgeting difficult or have big things they want to buy, like students who might need a computer for university, then it could be really useful for those kinds of purposes.”
While Lacey points out that BNPL apps don’t necessarily have to cause any harm, she also highlights a few risks to be cautious of.
“It can get into dangerous territory because you’re spending future-you money; money that you’re going to make from your profession, and sometimes it can be a problem when people overcommit,” she says.
“So, if people suddenly find they have to make a choice between meeting an essential versus paying off their debt, that’s when it becomes a problem, and we know that’s happening for 1 in 5 users already.”
As Lacey explains, failing to meet your BNPL repayments can also negatively impact your credit score—something students should watch out for.
A credit score is a number that tells lenders about your creditworthiness (how likely you are to pay back a loan based on your credit history). If you have a poor credit score, it could result in you being turned down by a lender.
“If you’re late multiple times or you never pay back your debt and incur multiple late fees, then a negative report can go on your credit rating,” she says.
“This can look bad when you go to apply for other things like a mortgage or a credit card, or even when you go to get a mobile phone plan.”
If you don’t feel super comfortable using BNPL apps, Lacey recommends giving yourself a “circuit breaker.”
“I say ‘circuit breaker’ as in don’t impulse buy with debt. If you’ve given it some thought, then any of the BNPL apps are good, but don’t use it on impulse buying if you can at all avoid it,” she says.
Additionally, Lacey suggests setting up your own “mini account” to help you save up for a big item yourself instead.
“Let’s say you wanted to buy something for $1,000 and you were going to use Afterpay with four payments of $250 every two weeks.
“Set up an automatic transfer to a separate account. Yes, that means you have to wait to get the thing, but you’re doing that same sort of process of paying for something little by little over a period of time.”
Want some more information on using BNPL apps responsibly? Good call.
By upgrading your membership to Student Edge Plus, you can access learning experiences from industry experts that’ll help you take control of your future. Money School has an entire course dedicated to finding out all the tea on BNPL apps.
Header Image: Anete Lusina via Pexels
Topics
Ref: 30bfaee3-148d-4eee-96c3-ad90008b944c
Most Popular
Comments & Feedback
Share your opinion
Emoji cheatsheet Formatting Comment guidelines
Wow,great suggestion,maybe will try